By Energy Worth Online
Security of supply emerged as the defining theme in global energy markets this week, as geopolitical tensions continued to disrupt oil, gas and electricity flows while governments and investors accelerated efforts to strengthen domestic and regional energy resilience.
From Nigeria’s expanding refining and gas capacity to Saudi Arabia’s efforts to reopen alternative oil-export routes, Qatar’s LNG vulnerabilities, India’s coal-stock pressures and Europe’s renewed reliance on coal, events across the energy system demonstrated how quickly geopolitical disruption can translate into higher prices and tighter supply.
Yet the week also showed that the energy transition has not stalled. Investment in gas, renewables, grids, refining and electrification continues to expand. What is changing is the context: energy security, affordability and reliability are increasingly influencing how the transition is being managed.
Nigeria: Refining, gas and renewables advance amid higher fuel costs
Nigeria provided several important signals this week about the direction of its energy sector. TotalEnergies and AMNI reached Final Investment Decision on the Ima Gas Development, an offshore project designed to produce approximately 350 million cubic feet of gas per day at plateau, with production expected to begin in 2028. The field will be connected by a 22-kilometre pipeline to Nigeria LNG on Bonny Island and is expected to provide roughly one-third of the gas required for the ongoing Train 7 expansion.

•President Bola Tinubu
The development is significant not only for Nigeria’s upstream gas industry but also for the country’s LNG ambitions. The additional supply will support Nigeria LNG’s planned expansion from 22 million tonnes per annum to 30 million tonnes per annum, reinforcing the role of domestic gas development in strengthening the country’s position in international gas markets.
Nigeria’s electricity system also recorded an improvement. Available generation reached about 5,403 MW on September 22, equivalent to roughly 93% of the country’s previous instantaneous peak generation record of 5,801.84 MW. The increase is encouraging, although available generation remains different from the electricity ultimately delivered to consumers, with transmission, distribution, gas supply and sector liquidity continuing to influence actual supply.
At the same time, Nigeria is expanding investment in distributed renewable energy. The $300 million Nigeria Distributed Renewable Energy Fund, launched commercially this week by the Nigeria Sovereign Investment Authority, Africa50 and Sustainable Energy for All, is designed to mobilise private capital into mini-grids, standalone solar systems and other distributed-energy solutions.

•Honourable Minister of Power, Joseph Tegbe commissioning a 581 kWp Interconnected Solar Mini-Grid system with a 1.4 MW battery storage system in Oke-Oyi Community, Ilorin East Local Government Area of Kwara State.
Together, these developments illustrate the increasingly diversified nature of Nigeria’s energy strategy: more gas, more refining, stronger grid capacity and accelerated deployment of distributed renewables.
Ruto’s Dangote visit highlights Africa’s refining ambitions
One of the week's most notable African energy developments came on September 25, when Kenyan President William Ruto visited the Dangote Petroleum Refinery in Lagos ahead of the planned groundbreaking of the Dangote-backed East Africa Oil Refinery in Lamu, Kenya.
Ruto’s visit was particularly significant because Kenya is preparing to develop a refinery with a planned capacity of up to 700,000 barrels per day, with the groundbreaking scheduled for September 30. The project has been reported at approximately $17 billion, although estimates have varied. It is intended to serve Kenya and wider East and Central African markets.
During his tour of the Lagos facility, Ruto pointed to the Dangote refinery as an example of what collaboration between governments, investors and financial institutions can deliver. The visit therefore carried significance beyond the two countries: it highlighted a broader African effort to capture more value from crude resources through domestic refining and regional petroleum infrastructure.
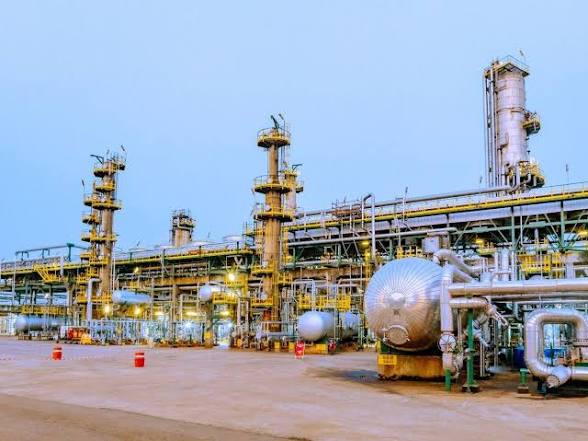
For Nigeria, the Dangote refinery is already altering the country's position in regional refined-product markets. Nigeria exported about $750 million worth of petrol in the first half of 2026, with the increase attributed in part to the refinery's operations.

President William Ruto with First Lady Rachel and Aliko Dangote in Lagos on September 25, 2026.
However, the refinery's scale has not insulated Nigerian consumers from global crude-price movements. Petrol prices have risen to around ₦1,400 per litre in Lagos and Abuja, while diesel prices have exceeded ₦2,000 per litre, even as the refinery operates at high utilisation. Reuters reported that Dangote's wholesale petrol price had also risen in response to higher crude costs.
The lesson is important: domestic refining can reduce dependence on imported refined products, but it does not eliminate exposure to international commodity prices.
Africa: infrastructure remains central to energy security
Across the continent, major energy projects continued to move forward despite the challenging global environment. In Tanzania, the long-delayed $42 billion LNG project has entered its final legal stage after negotiations on commercial, tax and revenue-sharing issues were concluded. The project is expected to represent one of Africa's largest energy investments and could significantly increase Tanzania's role in global gas markets.
Kenya's Lamu refinery adds another dimension to this investment trend. Alongside Tanzania's LNG development and Nigeria's refining and gas projects, it demonstrates that African countries are seeking infrastructure capable of supporting industrialisation, reducing import dependence and creating greater control over energy supply chains.
The challenge remains financing. Large-scale refineries, LNG facilities, pipelines and power infrastructure require substantial capital, long development timelines and reliable regulatory frameworks. The projects moving forward this week nevertheless suggest that energy security is becoming an increasingly important justification for such investments.
Middle East: Alternative routes cannot fully eliminate supply risk
The Middle East remained the principal source of global energy-market uncertainty. Saudi Arabia provided some relief to oil markets after restarting its East-West oil pipeline, which provides an alternative route for moving crude towards the Red Sea and the export terminal at Yanbu. The restart followed disruptions that had temporarily affected Saudi export flows.
The development highlighted the strategic value of alternative export infrastructure. The ability to move crude without relying entirely on the Strait of Hormuz gives producers greater flexibility during periods of geopolitical disruption. Saudi Arabia has also increased crude shipments through the Gulf as conditions have allowed.
Saudi Aramco is simultaneously placing greater strategic emphasis on natural gas. The company is planning a restructuring that would create a dedicated gas division alongside its upstream and downstream businesses. The proposed unit would focus on developing domestic gas resources and expanding Aramco's international LNG portfolio, while potentially creating opportunities for outside investment.
The message is significant: even the world's major oil producers are increasingly treating gas as a strategic component of their future energy systems.

Qatar's LNG vulnerability remains a global concern
Qatar's experience provides perhaps the clearest illustration of the vulnerability of concentrated energy infrastructure. Damage to the Ras Laffan LNG complex has disrupted part of Qatar's export capacity, while continuing uncertainty around the Strait of Hormuz has complicated the timing of the country's North Field expansion. QatarEnergy has said that the first North Field East train remains targeted for the first half of 2027, but further expansion depends on developments around the critical shipping route.
The disruption matters well beyond Qatar. LNG supplies from the Gulf are important to both Asian and European markets, meaning that interruptions can quickly translate into higher prices and fuel-switching decisions in importing countries.
Asia: high LNG prices strengthen the case for fuel diversification
Asian energy consumers continued to adjust to tighter LNG supplies and higher prices. Analysts expect Asian LNG demand to decline by 3% to 10% in 2026 compared with 2025, with Northeast Asia accounting for much of the reduction. Asian spot LNG prices have more than doubled to around $26/MMBtu since the conflict began.
For countries heavily dependent on imported gas, the price shock creates a strong incentive to conserve LNG, increase coal use where available, rely on nuclear generation or accelerate other forms of energy supply.
India provides a clear example. As of September 19, 74 coal-fired power plants, almost 40% of the country's coal fleet, had critically low stocks, according to government data. At the same time, electricity demand remained high, with peak demand hovering between 230 GW and 250 GW during the week.
Renewable generation in India rose by about 21% between April and August, but coal continued to play an important role in meeting round-the-clock electricity demand. The situation demonstrates the practical challenge facing rapidly growing power systems: renewable capacity can expand quickly, but dependable generation, storage, transmission and fuel availability remain essential to system reliability.
Global oil markets: Diplomacy and supply routes drive volatility
Oil markets remained highly sensitive to developments in the Middle East. On September 25, Brent crude settled at $104.32 per barrel, down 2.1% on the day, while West Texas Intermediate settled at $92.41. Prices fell as markets responded to renewed diplomatic activity between the United States and Iran and signs of improving Middle Eastern supply flows.
The week's price action illustrated the extraordinary sensitivity of crude markets to geopolitical developments. The reopening or restoration of individual supply routes can quickly ease prices, while renewed attacks or shipping disruptions can produce the opposite effect.
For energy-importing countries, the volatility reinforces the value of diversified supply sources, strategic reserves, domestic refining capacity and alternative transportation routes.
Europe: high gas prices revive coal generation
Europe is facing a particularly difficult energy equation as elevated gas prices increase the cost of electricity generation. European benchmark gas prices moved above €80/MWh this month, their highest level in three years, according to Reuters. Analysts expect European coal-fired generation to rise substantially over the coming six months as utilities respond to the deteriorating economics of gas-fired generation.
This is an important reminder that energy transitions do not always proceed in a straight line. When gas becomes prohibitively expensive or unavailable, power producers can turn to coal where existing capacity remains available.
The result is a tension between short-term energy security and longer-term decarbonisation objectives. Europe may continue investing heavily in renewables and electrification while temporarily relying more heavily on fossil fuels to maintain electricity supply during periods of market stress.
The transition continues — but the definition of resilience is changing
Despite the week's disruptions, the global energy transition remains firmly underway. The International Energy Agency expects global electricity demand to grow by 3.6% in 2026 and 3.8% in 2027, driven by industrialisation, electrification, electric vehicles, cooling demand and rapidly expanding data-centre consumption.
Renewables are also gaining ground. The IEA expects renewable electricity generation to overtake coal globally in 2026, with renewables' share of global generation rising from 33% in 2025 towards 37% by 2027. At the same time, nuclear generation is expected to increase, while grid expansion and system flexibility will become increasingly important as variable renewable generation grows.
The week's events therefore point to a more complicated energy transition than a simple shift from fossil fuels to renewables.
Countries are simultaneously pursuing oil and gas security, refining capacity, LNG infrastructure, coal and nuclear reliability, renewable generation, storage and stronger electricity grids. These investments may sometimes appear contradictory, but they reflect a common concern: ensuring that energy systems remain reliable and affordable while becoming progressively cleaner.
The week's takeaway
The central lesson from this week's energy markets is that energy security and the energy transition are no longer separate conversations.
Geopolitical disruptions have demonstrated how quickly concentrated supply chains can become vulnerabilities. Nigeria's refining and gas investments, Kenya's planned Lamu refinery, Tanzania's LNG project, Saudi Arabia's alternative oil-export routes and Europe's renewed coal generation all reflect different responses to the same underlying challenge: maintaining reliable energy in an increasingly uncertain world.
At the same time, renewable energy investment continues to accelerate, global electricity demand is rising and countries are expanding grids, storage and electrification.
The defining energy challenge, therefore, is not simply choosing between conventional and renewable energy. It is building energy systems that can deliver security, affordability and reliability today while steadily reducing emissions and increasing the share of cleaner energy tomorrow.
That is likely to remain the central tension — and opportunity — shaping the global energy landscape in the weeks and months ahead.